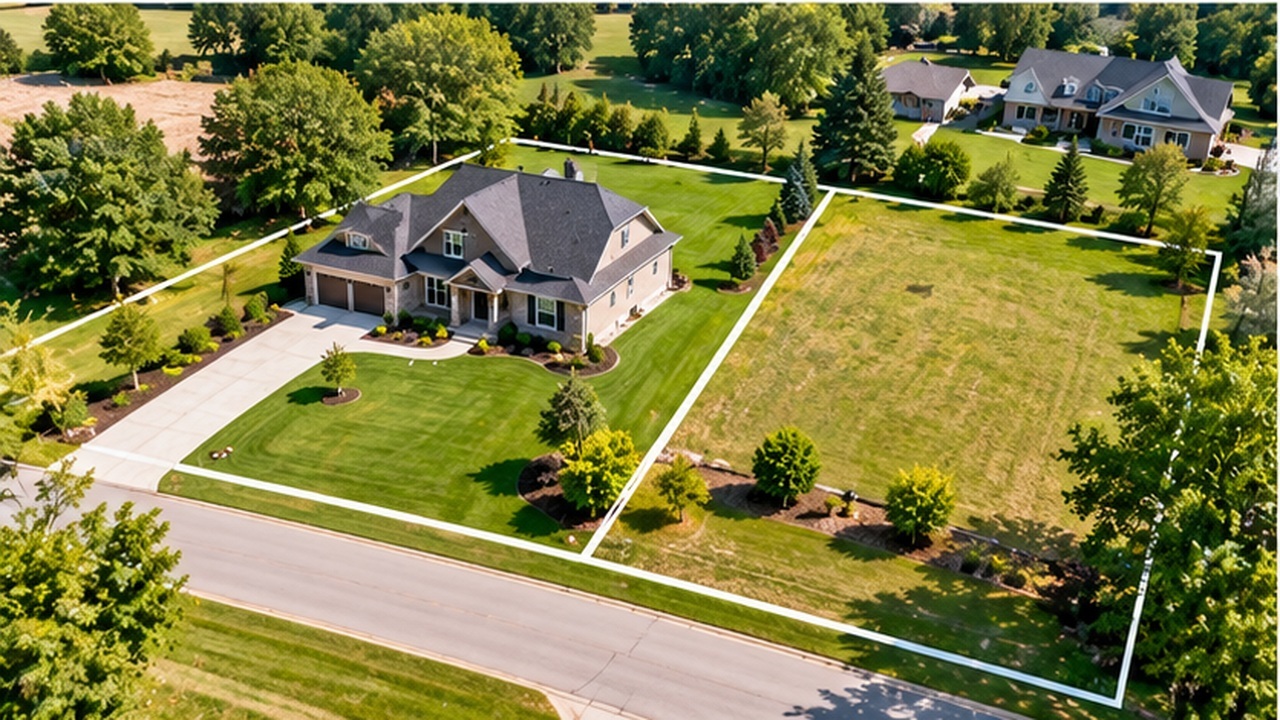
 Imagine finding a beautiful home that comes with an extra piece of land next door. Perhaps the additional lot provides more privacy, a larger backyard, or room for future improvements.
While this may sound like an attractive bonus, purchasing a home that includes multiple parcels can introduce mortgage questions that buyers might not expect.
What Does It Mean to Have Multiple Parcels?
A parcel is a legally identified piece of land, typically assigned its own property identification number by the local taxing authority.
Most residential properties consist of one parcel containing the house and surrounding land. However, some homes are marketed with two or more parcels that are being sold together.
For example, a seller might own a house on one parcel and an adjoining vacant lot on another. The two properties may function as one large yard, even though they remain legally separate.
This distinction can matter when a buyer applies for mortgage financing.
Why the Property Configuration Matters
Mortgage lenders need to understand exactly what property will secure the loan.
When multiple parcels are involved, the lender may need to determine whether the parcels can be included in the same mortgage transaction and whether the arrangement meets the loan program’s requirements.
Questions may arise about whether the parcels are contiguous, how they are legally described, and whether the additional land has separate development potential.
The lender may also review whether any parcel contains improvements, structures, or uses that could affect residential financing eligibility.
Simply advertising two parcels together does not automatically mean they can be financed as one property.
The Appraisal May Require Additional Review
An appraisal evaluates the property being offered as collateral for the mortgage.
When a home includes additional land, the appraiser may need to determine how that land contributes to the property’s overall market value.
A separate parcel does not necessarily increase the appraised value by the amount a buyer might expect.
For example, an adjoining lot with limited access or development restrictions may have a different market contribution than a parcel that can support another residence.
Comparable sales and local market conditions help determine how the additional land is valued.
Consider the Long-Term Implications
Buyers should also understand whether the parcels receive separate property tax bills, have different zoning classifications, or carry individual restrictions.
If they eventually want to sell the vacant parcel separately, they may need lender approval or a partial release of the mortgage lien, along with any required local approvals.
Before making an offer, buyers should ask for the parcel identification numbers, legal descriptions, and available property records.
Owning extra land can provide valuable flexibility, but buyers should confirm how that land affects their financing and future plans. Understanding the legal and mortgage implications early can help prevent unexpected complications before closing.